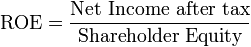This is default featured slide 1 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 2 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 3 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 4 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

This is default featured slide 5 title

Go to Blogger edit html and find these sentences.Now replace these sentences with your own descriptions.

Wednesday, June 16, 2010

How much money should I invest in Mutual Funds?


Every person should invest in Mutual Funds, except..

Mutual Fund investments are one of the best options for a beginner or even most advanced investors for investing in stock market. Although I pick and buy stocks of good companies myself, I also invest a portion of my money in Mutual Funds, and overall in my past years experience there is nothing I have found to regret about my investment strategy. In spite of all the talk on global recession, subprime etc. my investments made before the recession have earned good positive returns. If you are a beginning investor, I recommend reading the article Riding the Equity Wave for you. Having said this, the first step in investing is to decide how much to invest in mutual funds or stock markets. In my opinion every person should invest in Mutual Funds or stock markets except those who do not have any risk appetite. And here's a simple recipe to find your 'monthly risk appetite'.

Determining your monthly risk appetite

No matter, how many success stories you hear, mutual fund or stock market investments are always risky, especially in the short term. In other words, the principal you invest is at a 'risk'. For e.g. Rs. 1Lac invested on Dec 2007 in most Mutual funds was less than Rs. 50K a year after that (but now it is more than Rs. 1Lac again). Thus you simply cannot invest money from your salary that you need in the near future (say 5 years). Use the following simple formula.

Monthly Risk appetite = portion of your monthly income you can you set aside for the next 5 years

Let me give you my example. My current monthly salary is Rs. 45K. Including expenses for me and my wife, plus a monthly support i give to my parents, my expenses are around 15-20K. Apart from this my wife and I are expecting a baby in the coming year and we also plan to buy a car. For this, in addition to the savings I already have, I am saving at the rate of 5K per month. This takes out about 25K from my salary. For emergencies, add an additional 5K-10K per month. So I am left with around 10K from my monthly salary which I will not need in the coming 3 to 5 years. So my monthly risk appetite is around 10K. Note that I already have enough savings to support me and my family for 2 years,

In similar manner above, you should first determine a monthly amount you can set aside for the next 5 years. Remember to take into account all possible emergencies and also save at least 10-20% of your salary in safe investing options like fixed deposits or bonds. So after reading this paragraph, we assume you can now calculate your monthly risk appetite. lets move on to the next step.

Keeping a margin for stock market collapse

An obvious choice would be to invest all the money you have set aside in the above step in mutual funds or stock markets. I however recommend that you keep aside some portion of it (say 10% - 25%) further for investing when the stock market crashes. Remember that money invested in stock market crash gives much more returns than investments made when the stock market is at its peak (obviously). I follow the simple rule that whenever the stock market falls below 15% from its peak value, I invest about 20-25% of the money I have set aside for stock market crash.

Start an SIP - Systematic Investment Plan

It is best (risk-minimizing) to make small investments every month rather than large lump-some investments in Mutual Funds. Lump-some investments are also great if they are made when the stock markets crash. Thus from the above two step you now know how much to invest in Mutual Funds every month - simply

Monthly Mutual Fund investments = You 'monthly risk appetite' x 0.8

Start an SIP once you determine your risk appetite. The 20% of the cash you set aside from your monthly risk appetite can be set aside and kept in a bank and invested only if the stock market crashes. This simple strategy can work wonders if followed for a stretch of 5 to 10 years.

Tuesday, June 15, 2010

Crisil Mutual Funds CPR Ratings - what they tell us


Crisil - Credit ratings agency

Crisil is a credit rating agency which rates various companies for their ability to repay back debt. You can read about more about Credit rating agencies here. In addition to this, Crisil also rates mutual funds. Crisil is a well known and reputed company and is a market leader in India (followed by ICRA). Thus the ratings assigned by CRISIL can be taken seriously.

CRISIL CPR ratings

The ratings assigned to Mutual Funds by Crisil are CPR1, CPR2, ... with CPR1 being the topmost rating - for the Best Mutual Fund, according to predetermined criterion used by Crisil. Crisil uses the following criterion to rate a mutual fund.
  1. Past Performance of the Mutual Fund as compared to its peers in the past 2 years - (75% weightage)
  2. Sector concentration of the portfolio of that Mutual Fund
  3. Industry concentration
  4. Liquidity
Note that the rating is not merely on the basis of past performance. Thus a BEST Mutual Fund according to CRISIL CPR ratings may not be the best performing mutual fund. However the other factors considered in the rating are criterion are also important as they are 'risk-minimizing factors'. It is best to split your investments in 2 to 5 mutual funds to further minimize risk (all having CPR 1 ratings). I highly recommend investing in Mutual Funds with CPR 1 ratings, unless you know what you are doing.

To find out the best rated Mutual Funds by CRISIL, click on CRISIL CPR ratings.

Choosing the best from different Fund Families

Crisil groups mutual funds into different categories, Large Cap, Equity Diversified, Small and Midcap, and assigns ratings within each category. if you do not know what category to choose, it is always best to choose "Equity Diversified" (unless you are doing it for a tax saving purpose, in which case you should go for Tax Saving ELSS funds). If you have a larger investment appetite, then I recommend investing in 2 to 3 Equity Diversified Mutual Funds and one Midcap/Small cap Fund.

Sunday, June 13, 2010

DSP BLackRock Micro Cap Fund Review and latest news


DSP BlackRock Micro Cap - Introduction

DSP BlackRock Micro Cap Fund is the best mutual fund in 'equities diversified' category (best as per according to NSE MF Tracker. Note that this rating 'best' is only based on the past performance of the mutual fund, unlike CRISIL CPR ratings which not only take into account not just performance but also other risk minimizing factors like sector concentration, industry concentration and liquidity. However, DSP BlackRock Micro Cap Fund is not rated by Crisil yet. In any case, I personally think that this is the one of the best mutual funds to invest in (especially SIP - Systematic Investment Plan) in the coming years. Moreover, this mutual fund makes an even more attractive investment options in view of the latest news (see below) which says that DSP Blackrock Micro Cap Fund will now be converted into an open ended scheme. Earlier SIP in this scheme was not possible. Below are some of the highlights of this micro cap mutual fund scheme.

Highlights and key points of DSP BlackRock Micro Cap Fund

  1. Open Ended scheme - with no entry and exit load. An exit load of 0.25% will be charged if units are redeemed before 7 days.
  2. Investment idea - Micro Cap Stocks - DSP Blackrock Micro Cap Fund invests company's which are 'small' in the sense that these companies do not belong to the top 300 companies by market capitalization. Let us call these stocks as micro cap stocks. According to information on Blackrock page, 65%-100% of the portfolio will consist of micro cap stocks while 0-35% of the portfolio may consists of other equities. Click on DSP BLackrock micro cap portfolio to check out its portfolio at various available dates in the past.
  3. Fund Recurring expenses - The fund recurring expenses are about 2.5% (annual).
  4. Mutual fund Past performance - Click on DSP BlackRock Micro Cap NAV and past performance to find out more.

DSP Blackrock Micro Cap Fund now an open ended scheme from June 15 2010 - latest news

The following is an announcement directly on DSP blackrock funds page.

DSP Merrill Lynch Mutual Fund News
DSP BlackRock Mutual Fund has announced that DSP BlackRock Fund, which is currently a close ended scheme, will be converted into an open ended scheme. The change will be effective from 15th June, 2010. The scheme will offer regular and institutional plan with growth option. The minimum application amount under regular plan is Rs. 1000 and for institutional Rs.5 crore. The scheme will be managed by Mr. Apoorva Shah and Mr. Vinit Sambre. The scheme will charge 0.25 per cent exit load, if units are redeemed within 7 days from the date of allotment. Investors, who do not agree to the revision, have an option to redeem or switch their units on or before 14th June, 2010 without paying any exit load.

Saturday, June 12, 2010

Understanding ROE, ROCE and Shareholder's Equity


Return on Equity (Return on Net worth)

Return on Equity (ROE), also called as Return on Net Worth, is one of the key financial ratios which indicates how well the management has been efficient in managing the company's assets. In my early days in the investing world, this is the ratio which confused me the most. Return on Equity is defined by the following formula

Return on Equity
What is confusing in the above formula for beginners is the meaning of 'Shareholder's equity'. Shareholder's equity should not be confused with 'total value of all the equities, i.e. shares'. The later is called market capitalization of the company. Shareholder's equity is defined by

Shareholder's equity = Total Assets - Total Liability

In other words, Shareholder's equity is nothing but the amount of money that the company would be worth if it were to go bankrupt at this very moment. This is also called as book value.

How to calculate ROE?

In order to calculate ROE, Return on Equity, lookup any financial portal or the company's annual report for the following
  1. EPS - the earning per share of the company.
  2. Book Value - The book value of the company per share (i.e. shareholder's equity divided by the number of shares).
Then to calculate ROE you simply divide EPS by Book Value. ROE is typically expressed as a percentage (i.e. multiply by 100 and put a "%" sign).

Example of Return on Equity : Let us say a company earns Rs. 100 per share and the book value of the company is Rs. 300. Then the Return on equity is 33.3%.

Typical values of Return on Equity and what it means

As a general rule of thumb, you should be careful while investing in any company whose ROE is less than 10%. I personally prefer stocks which give a return on equity of at least 20% or more. Obviously return on equity is a direct measure of how well the company is generating cash with the amount of 'shareholder's money' it has. There is one more thing which ROE tells you and which most financial websites don't mention. ROE also tells you how easy it is for the company to profitably expand its business. For example, let us take a situation where the company does not have any debt. Then an ROE of 25% means that the company is producing Rs. 25 for every Rs. 100 of assets it has. Thus if the company were to expand its business, then for every Rs. 100 spent on expansion, it would earn Rs. 25, which is greater than the usual interest rates. If ROE is roughly the same as the bank interest rates, then it means that even if the company expands, it will take a long time for it to make its investments in expansion profitable.

Variations: Return on Average Equity

The Book Value of a company can significantly change during a given year. In these circumstances, one can calculate the average book value (average of the book value in the beginning of the year and at the end of the year) and use it to calculate ROE.

What ROE does not tell you

ROE, like any other financial ratio is very far from being perfect. For example, ROE does not tell you anything about the debt of the company. As explained before it does say something about the potential of the company to expand its business, but does not actually tell you anything about the possible or expected growth of the company. Nevertheless, ROE is a very basic ratio, and used in addition with few other indicators like topline growth and financial ratios like P/E, Debt/Equity and profit margins can give a reasonable good and quick overview of the company.

ROE versus ROCE

A related ratio to Return on Equity is Return on Capital Employed (ROCE) or also called by the name of Return on Capital Invested (ROCI). ROCE is defined to be

ROCE = Operating Profit / Capital Employed.

Operating Profit means profit before tax, depreciation, interest and exceptional items. While Capital Employed is the cash (& assets) that was actually used to do the business in that year. The formula for calculating Capital Employed is

Capital Employed = Total Assets - Current Liabilities

Note that Current Liabilities are those liabilities which the company has to meet immediately (in the coming year). ROCE can sometimes give a slightly accurate picture than ROE, but I have found that overall if you look at the values of ROE for the past 5 years, you get roughly the same picture of the company as you would get by looking at values of ROCE. Moreover, ROE is easier to calculate.

Friday, June 11, 2010

Topline vs BottomLine Growth - what is a better indicator? Investment Basics)


Topline vs Bottom Line Growth

(Anticipated) Growth of a company is an extremely important parameter in deciding the valuation of the company's stock. When a company grows, there are however various parameters which 'grow' when a company 'grows'. Among the most important of these are
  1. Growth of a company's sales - This is called as Topline Growth for the simple reason that in accounting the sales of a company are written on the first line 'top line'.
  2. Growth of company's net profit - This is called as Bottomline Growth, for the simple reason that Net profit of a company is written at the bottom, after writing figures of sales, expenditures, revenues, interest, depreciation, tax, etc.

Topline vs bottomline - simple example

Topline growth, or growth in sales represents the potential for the business to grow. Bottomline growth or growth in net profit, however can be caused either by increase in sales, or decrease in expenditure/raw material or various combinations including exceptional items (i.e. items which are one-time expenditures/income). Let us take the example of a steel company. If its sales grow by 25%, then topline growth is 25%. It show that the demand for steel, the basic output of that company is growing by 25%. However, it could happen that at the same time, prices for raw material, in this case coal or iron ore also go up by 15%. Other factors remaining same, the increase in net profit will be much less than 25%.

What number to look at while analyzing a stock - topline or bototmline ?

As far as getting an idea of how the company is growing, i think it is a good idea to look at topline growth. Various factors which come into play while calculating bottomline growth (e.g. raw material costs, etc.) are also important, but in my experience i have found it very convenient to analyze them by looking at financial ratios like operating profit margins (or ebitda margins) or net profit margins.

Monday, June 7, 2010

How to buy stocks in USA, China or overseas from India?


Indian Investors looking to invest in stock markets abroad

Have you been looking for investing opportunities beyond the Indian Stock markets (NSE, BSE)? For e.g. investing in Oil ETFs, or other mutual funds exclusively available in select developed countries like United States or Europe, UK, etc? Or thinking of buying stocks in China? Read on.. the answer to these questions is much simpler than what one would have imagined.

RBI allows $25000 foreign investment per annum

RBI has several restrictions on buying and selling rupee. For example, you are still not allowed to trade forex in india, unless it is for hedging purpose. However, fortunately, RBI has allowed every indian to invest up to $25000 overseas. This means you can use this much money to either buy real estate, stocks, mutual funds, or simply put that money in a savings account in USA, China or any other country (this last option does not make economical sense, because interest rates in India are higher). Thus trading in stocks in world markets either in USA, Japan, China, Europe, or any other country is now extremely Easy. All you do is start by registering with an online broker who allows you to trade in world markets of your choice.

Registering with an Online broker

An example of such an online broker is Interactive Brokers. This is just one example. There are several other online brokers which allow you to trade in world wide markets from India. Even ICICI Direct allows you to invest in stocks in USA or other countries. Google a little or keep your eye on advertisements. Good brokers usually advertise aggressively highlighting their plus points. The following things need to be kept in mind.
  1. Trading in world markets may require a larger appetite. For example when you open an account with Interactive brokers, you have to start with $5000 for investing in world markets like NYSE.
  2. There is a verification procedure when you open your account where you may have to submit/post some documents. The overall approval procedure may take a couple of days or more.
  3. The money you invest in foreign stocks is kept in dollars (or other currency). Thus apart from stock market fluctuations you are also exposed to the risk of currency fluctuations.

Sunday, June 6, 2010

Godrej Consumer Products (GPCL) - best FMCG stock


Godrej Consumer products - best FMCG stock

Godrej consumer products is a leading FMCG company based in India which manufactures soaps, personal and hair care items, and other home care products like insecticide, hand sanitizers, etc. Some of the popular brands of Godrej include Cinthol (soap), Renew (Hair Color), Colour Soft (Hair Color), Hit (insecticide), Goodknight (mosquito repellent - insecticide), Brylcream (hair styling gel), etc.

Godrej 3x3 strategy and recent acquisitions

Godrej Consumer products has been talking about its 3 x 3 strategy - a strategy to spread to 3 continents (Asia, Africa, South America) in 3 areas of Home Care, Personal Care and Hair care. Godrej has been aggressive in its expansion plans to the above mentioned continents (frequently referred to as the emerging markets) and its recent five acquisitions include
  • Acquisition of the Issue group (hair color) in Latin America.
  • Acquisition of Tura Brand in Nigeria.
  • Acquisition of Megasari group in Indonesia.
  • Acquisition of the remaining 51% stake in Godrej Sara Lee (a joint venture)
  • Acquisition of Argencos (hair styling cream) in Latin America.

Godrej Consumer products - stock price and financials

Godrej consumer products stock is currently (as I write this post) selling at a price of about Rs. 343 which is at about 40 P/E. 40 P/E is very high. It looks likely that godrej will grow at about 20-25% in the coming years, which vaguely speaking justifies a P/E of about 20-30. However, despite the high P/E, the stock seems to be cheap, especially because of its current acquisitions. According to a press release by Godrej, it expects to see revenues of Rs. 4000 crore in the coming financial year as a result of the coming acquisitions. This is more than 3 times its current revenues. This together with the anticipated growth of 20% in the coming years points out about 50% possible upside in this stock. The debt arising from the above acquisitions is not likely to decrease the valuations so much because of a healthy ROCE (of about 30%). Especially because of the acquisition and the current valuations, this stock is likely to provide over 30% returns per annum for the next two years.

Competition with HUL

Hindustan Unilever remains a market leader in several segments (like soap) in India. However HUL seems to be slowly loosing its market share to Godrej, which has slightly less expensive prodcuts. Moreover profit margins of Godrej are significantly higher than those of HUL. This is what makes GodrejCP one of the best FMCG stocks available right now in Indian stock market.


Recent Posts related to the theme "Best Stocks to Buy Now" (2010)


Stocks which were "Best Stocks to Invest" for year 2009, but now, the analysis may or may not apply, as prospects for the current year have changed.
Posts on Investment Basics
  • Understanding the P/E Ratio
  • Return on Equity (ROE), ROCE and Shareholder's Equity
  • Consolidated results vs. Standalone Results.
  • Topline Growth vs Bottomline Growth

  •